The complete personal finance app for financial resilience
Am I wealthy for my age?
There’s no official net worth that makes someone wealthy. Enter your age and net worth below for your real percentile among households your age, from the Federal Reserve’s 2022 Survey of Consumer Finances, then see it beside three sourced answers to what “wealthy” means, which disagree by about seven times.
WealthAge is a personal finance app, on the same shelf as Copilot Money and Monarch Money. Your accounts, transactions, spending, cash flow and net worth live in one place, kept traceable to where every number came from.
Your result
Enter your own age and net worth above and this example becomes your result.
Example percentile
A household aged 45–49 with $500,000 is higher than about 68% of households in that band.
Federal Reserve SCF 2022.
Ranked against households, the unit the Federal Reserve measures. If you entered one person’s accounts rather than a household’s, this percentile reads high.
Your age band, for comparison
The top 10% of households aged 45–49 starts around $1,428,900; the top 1% floor is about $8,754,000.
Federal Reserve SCF 2022, computed by WealthAge; the full twelve-band table is below. Neither line is a WealthAge-invented threshold for “wealthy.”
This percentile comes from Federal Reserve data for your age band. It describes a group of households, not you, and it is not a definition of “wealthy” on its own; see the sourced lines below.
This is a useful estimate. Your complete financial picture may change it.
WealthAge can calculate this using your actual accounts, obligations, cash flow and resilience, and keep it updated as your life changes.
Connect or upload, and see your net worth from your real accounts, with any stale connection flagged.
See how it worksWhat “wealthy” means
Three sourced answers to what “wealthy” means disagree by about seven times
- Perceived “wealthy” (Schwab Modern Wealth Survey, 2025)
- $2.3M
- Top 10% of U.S. households (Federal Reserve SCF 2022)
- $1,936,900
- Top 1% of U.S. households (Federal Reserve SCF 2022)
- $13,615,400
The first line is a perception, not a distribution statistic: Charles Schwab’s Modern Wealth Survey (most recent published edition June 2025, re-checked for a 2026 edition on 14 August 2026; none has published) asked roughly 2,000 Americans what net worth they think it takes to be wealthy. It moves by generation: Gen Z respondents said $1.7 million, Baby Boomers said $2.8 million. The other two lines are measured, not asked: cutoffs in the actual 2022 distribution of U.S. household net worth, computed by WealthAge directly from the Federal Reserve’s public Survey of Consumer Finances microdata (4,595 households sampled, weighted to represent about 131 million U.S. households) and verified against the Fed’s own published historic table.
The three lines span $1,936,900 to $13,615,400: the top 1% cutoff runs about 7 times the top 10% cutoff, and about 5.9 times the survey’s perception line. The perception line itself sits only about 19% above the actual top 10% cutoff, close enough that what Americans feel is wealthy tracks roughly where the real top decile begins. No official definition picks one of these three as correct, because they are not measuring the same thing.
The honest answer
There is no official “wealthy” line. Your percentile is the measurable one.
Your own percentile, computed from the same public data, is the one number here that actually describes where your household stands.
That’s what the calculator above is for. It won’t hand you a single WealthAge threshold for “wealthy.” It puts your real number next to the sourced lines that already exist, and you judge which one, if any, fits you. A household at the 68th percentile for its age sits closer to typical than to any of the three lines above. One at the 90th sits right at the Federal Reserve’s own top-decile cutoff, the line closest to what Americans mean when they say wealthy.
The twelve age bands
What net worth puts your age band in the top 10%, or the top 1%?
The all-households figures above blend every age together; a 30-year-old and a 65-year-old reach the top 10% at very different balances. This table splits the same underlying Federal Reserve microdata into the twelve age bands the calculator above uses, so you can check your own age band’s cutoffs directly, or set your own numbers in the calculator for an exact percentile instead of reading a column by eye.
| Age band | Households (N) | Top 10%* | Top 1% (floor)† |
|---|---|---|---|
| 18–24 | 111 | $190,800 | $825,200 |
| 25–29 | 211 | $291,700 | $2,127,000 |
| 30–34 | 291 | $537,800 | $2,777,400 |
| 35–39 | 352 | $870,600 | $4,852,100 |
| 40–44 | 411 | $1,189,500 | $7,020,000 |
| 45–49 | 396 | $1,428,900 | $8,754,000 |
| 50–54 | 424 | $2,530,100 | $12,858,900 |
| 55–59 | 490 | $2,653,700 | $15,602,000 |
| 60–64 | 536 | $3,021,000 | $17,865,000 |
| 65–69 | 492 | $2,898,500 | $21,698,700 |
| 70–74 | 374 | $2,997,400 | $18,628,000 |
| 75 or older | 507 | $2,699,000 | $17,726,300 |
Values rounded to the nearest $100; a ~4,600-household survey cannot support finer resolution. *Above the 90th percentile, Federal Reserve sampling error grows quickly; read this column as approximate. †Above the 99th percentile the survey sample is too thin for a precise cutoff; read this column as a floor, not an exact line. The 18–24 band (N=111) is the thinnest of the twelve; read both of its columns as indicative only.
Each band’s cutoff is estimated from roughly 400 sampled households, so neighbouring bands do not form a smooth ladder: the step from 45–49 to 50–54 is 77%, and the top 10% column falls between 60–64 and 65–69. Read a band’s cutoff as that band’s own estimate, not as a threshold that moves on a birthday.
Figures are 2022 dollars, the Federal Reserve’s survey year. WealthAge’s standing June 2026 inflation adjustment (a 1.1411 CPI-U factor, detailed on the net worth by age page) is not applied here, so every cutoff stays a direct, unadjusted read of the 2022 survey.
Source: the Federal Reserve’s 2022 SCF Summary Extract public microdata file, downloaded from the Federal Reserve and processed by WealthAge, verified against the Fed’s own published historic table on 9 August 2026. Not the Fed’s own printed bulletin figures, which come from a different, internal dataset; see the net worth by age page’s methodology for the distinction.
Wealthy versus prepared
Wealthy for your age is not the same question as prepared for a shock
WealthAge is web today, built for your phone’s browser. A percentile answers where your net worth sits against other households your age, in one moment, using public survey data. It says nothing about whether that money would carry you through a job loss, a medical bill, or a bad year. Those are different questions, decided by what you could actually reach and what you owe every month, not by a single balance.
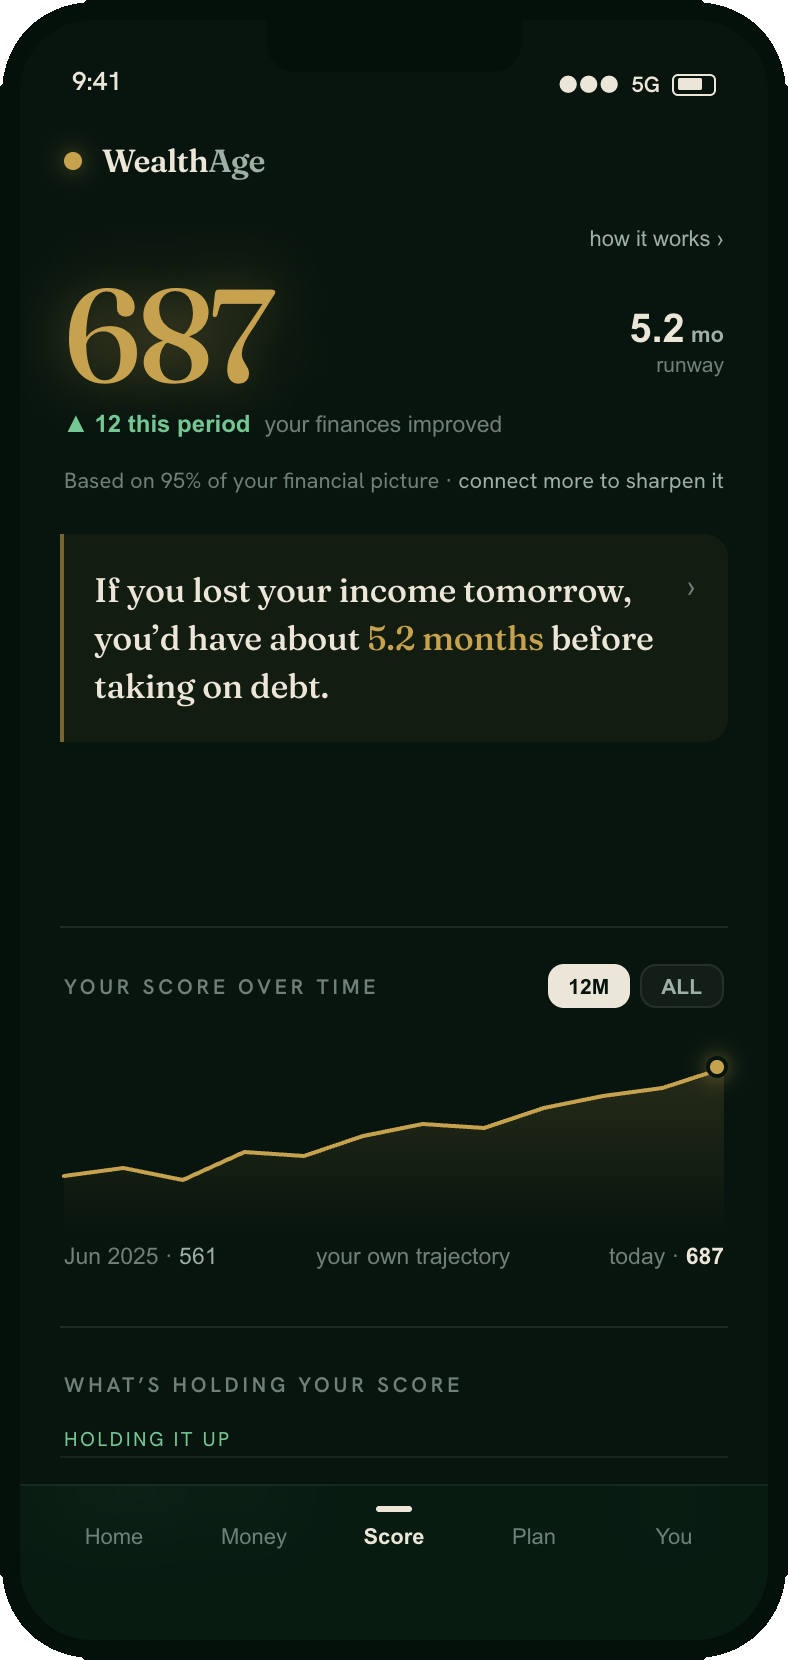
Your WealthAge Resilience Score reads how prepared your finances actually are: what you could access quickly, what keeps draining, and what would replace your income if it stopped. This page just ranked you against other households. Your WealthAge score never does, because a percentile and your WealthAge score answer two different questions. See an estimate of your score at the free score estimator, or check a related number directly at the savings runway calculator.
Connect or upload, and see how prepared your finances actually are.
Limits
These figures describe a population in 2022, not your situation today
None of the arithmetic above, the percentile, the cutoffs, or the three sourced lines, is a complete picture. Here is what it can’t tell you.
Sampling. The Federal Reserve’s Survey of Consumer Finances samples roughly 4,600 households and weights them to represent about 131 million U.S. households. That’s a sound methodology for the middle of the distribution and a noisier one at the very top, where a handful of extremely wealthy sampled households can shift the top-decile and top-percentile cutoffs substantially.
Vintage. These are 2022 figures. Household wealth, and Schwab’s survey, have both moved since. The next SCF wave is expected to publish in late 2026; this page is re-issued when it does.
What the calculator can’t see. It only sees the age and net worth you type in. It has no visibility into your income, your debts, your insurance coverage, or how quickly your specific assets could actually convert to cash. A percentile is a position, not a plan.
Methodology
Every figure on this page traces to a dated source
Your percentile and every cutoff in the table above read from the Federal Reserve’s 2022 SCF Summary Extract public microdata file, downloaded from the Federal Reserve and processed by WealthAge, computed and verified against the Fed’s own published historic table on 9 August 2026. The full pipeline, its validation against the Fed’s tables, and its sampling limits in more depth are documented on the net worth by age page’s methodology section, which this page does not repeat. The calculation runs in your browser; the figures you enter are never sent to WealthAge.
The perception line comes from Charles Schwab’s Modern Wealth Survey, 2025 edition (published June 2025); figures confirmed against four independently published reports on 14 August 2026, Schwab’s own PDF not reachable from our systems. This page is re-issued when the next SCF wave publishes, and every figure is re-checked against its published source at that point.
Data: Federal Reserve SCF 2022 (published Oct 2023); Charles Schwab Modern Wealth Survey, 2025 edition (published June 2025). Published 14 August 2026.
Corrections: 2026-08-14: first publication.
Questions
Seven questions come up most about being wealthy for your age
Is there an official net worth that makes someone wealthy?
No. No government agency, and no single widely accepted study, sets a net worth threshold for "wealthy." Three real, sourced lines answer close but different questions: what Americans say wealthy means (Charles Schwab's Modern Wealth Survey, most recent edition 2025: $2.3M), what net worth actually puts a household in the top 10% of the country (Federal Reserve SCF 2022, computed by WealthAge from the public microdata: $1,936,900), and what puts a household in the top 1% ($13,615,400). They disagree by about seven times between the widest two. This page shows your own percentile instead of picking one of the three as the answer.
What net worth is considered wealthy in 2026?
The most recent published edition of Charles Schwab's Modern Wealth Survey (June 2025; re-checked 14 August 2026, and no 2026 edition has yet published) found Americans believe it takes $2.3M in net worth to be considered wealthy, and $839,000 to be "financially comfortable." Both are a perception average from a survey of roughly 2,000 Americans, not a statistical threshold: Gen Z respondents set the bar at $1.7 million and Baby Boomers at $2.8 million, so the "average" hides a wide generational spread.
What net worth puts a household in the top 10%?
$1,936,900 across all U.S. households (2022 dollars), computed by WealthAge from the Federal Reserve's 2022 Survey of Consumer Finances public microdata and verified against the Fed's own published historic table. By age it runs from $190,800 in the youngest band to $3,021,000 at its peak; the twelve-band table on this page states every cutoff.
What net worth puts a household in the top 1%?
$13,615,400 across all U.S. households (2022 dollars), same source and method as the top 10% figure above. The Federal Reserve's own documentation flags the survey's sampling error as large above the 90th percentile and larger still above the 99th, so read this and every top-1% cutoff in that twelve-band table as an approximate floor, not a precise line.
Why do "wealthy" net worth figures disagree so much?
Because they answer different questions on different bases. Schwab's $2.3M is what people feel wealthy means, averaged across a survey. The Federal Reserve's $1,936,900 top-10% cutoff is a measured line in the actual distribution of household net worth. Its $13,615,400 top-1% cutoff is a much rarer line in the same distribution, pulled up by a small number of very large fortunes. None of the three is wrong; they are not the same measurement, which is why no single number can honestly answer "am I wealthy" for everyone. Your own percentile, computed from the same Federal Reserve data, is the only one of these figures that describes your household rather than a population.
Does a high net worth percentile mean I could handle a job loss or a bad year?
Not by itself. A percentile compares your net worth to other households your age, in one moment, using public survey data; it says nothing about how much of that money you could actually reach quickly, what you owe every month, or what would replace your income if it stopped. That is a different, more specific question, and it is what your WealthAge score reads instead of a percentile.
Why is this 2022 data?
The Federal Reserve fields its Survey of Consumer Finances every three years: 2019, then 2022, with the next wave, SCF 2025, expected to publish in late 2026 (see the standing re-issue commitment in the limits section above). Faster-looking numbers exist, but none replace it for a real percentile. The Fed's own Distributional Financial Accounts update quarterly, but they track total household wealth across the whole economy, not a representative sample of individual households, so they cannot produce a percentile at all. App-dashboard averages cover only the people using that app, a self-selected group already engaged with their finances. Perception surveys, like the Charles Schwab Modern Wealth Survey already cited on this page, ask what people think "wealthy" means, not what households actually hold, which is why this page treats that figure as a separate, perception-based line rather than a percentile source. The SCF remains the only source built to produce a representative percentile. Checked 14 August 2026: no newer wave has published.
Wealthy has no single number. Your percentile does.
Three sourced lines disagree by about seven times, and no official definition picks one. Your own percentile, from the same public data, is the one figure on this page that actually describes your household.
One limit, plainly: the calculator sees only the age and net worth you type in, and your percentile only places that number against public data. WealthAge brings the same numbers into the same place as your real accounts, connected or uploaded, instead of a form you fill in once.
WealthAge recomputes this from your connected or uploaded accounts, and tells you when a number is stale or a connection has stopped.
Connect or upload to start.
See how it works