The complete personal finance app for financial resilience
How long will my savings last?
Divide what you could actually reach by what you'd have to spend, and that answer is your runway: $18,000 against $4,500 a month lasts exactly 4 months. Drawing down a retirement balance is a different question, one a real rate of return changes by years, not months.
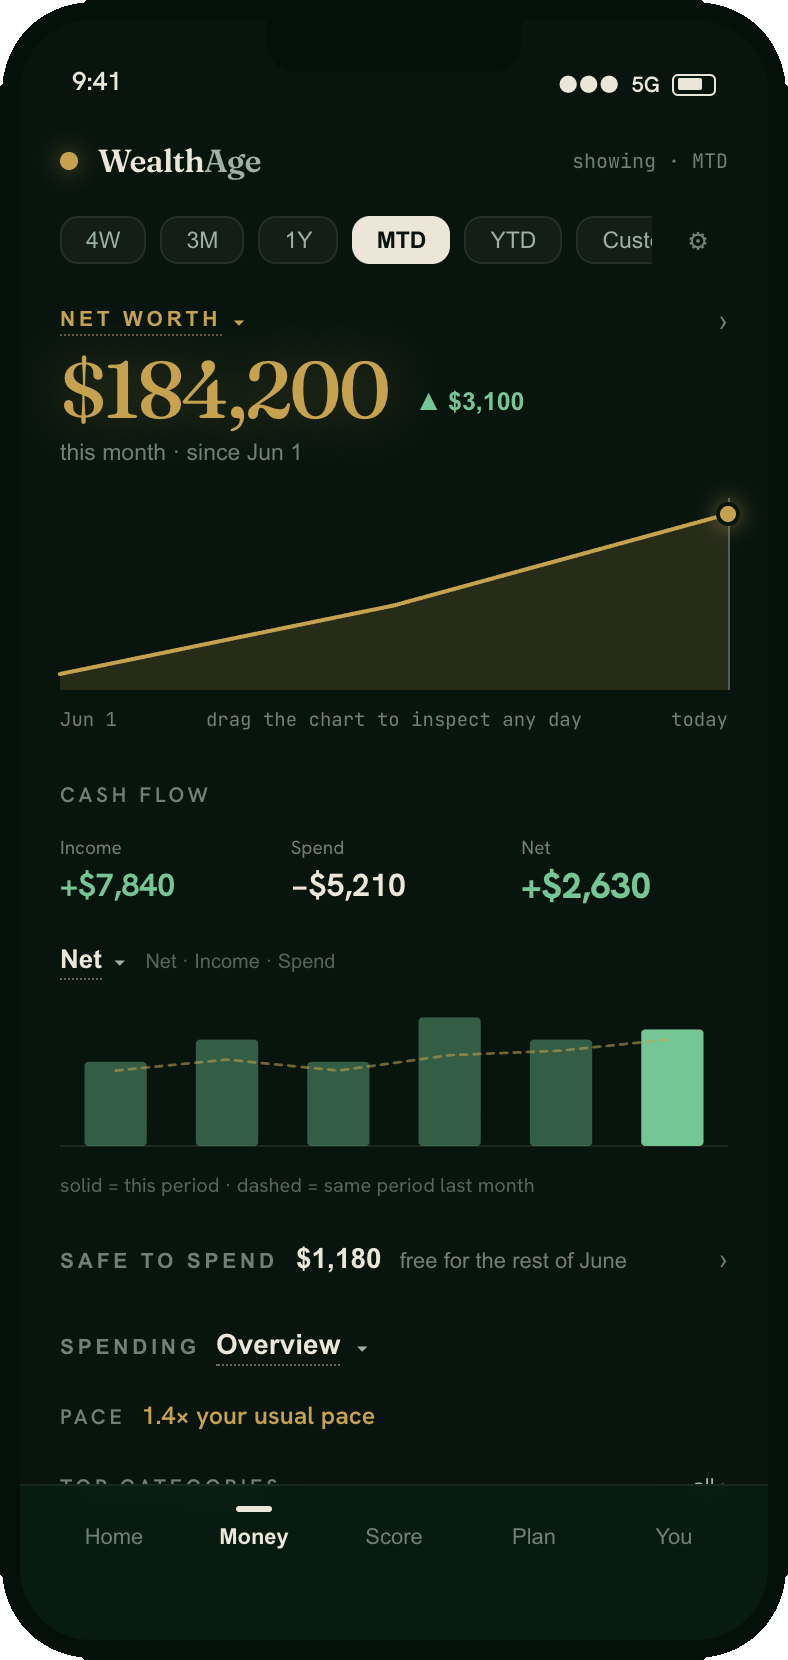
WealthAge is a personal finance app, on the same shelf as Copilot Money and Monarch Money. Your accounts, transactions, spending, cash flow and net worth live in one place. WealthAge reads how long that money would last if the income behind it stopped.
The runway grid
Savings runway is savings divided by spending, nothing more
Every cell below is that one division, savings across the top rows against essential spending along the columns. No growth, no inflation, no market assumption: every cell is reproducible on a pocket calculator.
| Savings | $2,000/mo | $3,000/mo | $4,000/mo | $5,000/mo | $6,000/mo | $8,000/mo |
|---|---|---|---|---|---|---|
| $10,000 | 5.0 mo | 3.3 mo | 2.5 mo | 2.0 mo | 1.7 mo | 1.3 mo |
| $25,000 | 12.5 mo | 8.3 mo | 6.3 mo | 5.0 mo | 4.2 mo | 3.1 mo |
| $50,000 | 25.0 mo | 16.7 mo | 12.5 mo | 10.0 mo | 8.3 mo | 6.3 mo |
| $100,000 | 50.0 mo | 33.3 mo | 25.0 mo | 20.0 mo | 16.7 mo | 12.5 mo |
| $250,000 | 125.0 mo | 83.3 mo | 62.5 mo | 50.0 mo | 41.7 mo | 31.3 mo |
| $500,000 | 250.0 mo | 166.7 mo | 125.0 mo | 100.0 mo | 83.3 mo | 62.5 mo |
| $1,000,000 | 500.0 mo | 333.3 mo | 250.0 mo | 200.0 mo | 166.7 mo | 125.0 mo |
Every cell is total savings ÷ monthly spending, rounded to one decimal month. Independently re-derived and checked cell for cell before every deploy; see the methodology below.
This grid holds for a horizon of months to a few years. Past roughly ten years the number quietly stops holding, because it assumes the money earns nothing and prices never rise while it sits. The retirement scenarios table below answers the long-horizon version of the same question, with a real rate of return built in.
Retirement drawdown
A retirement balance lasts years longer or shorter than flat math says
Money that stays invested keeps earning while it is spent down, so the flat grid above understates a retirement balance’s true runway. Below, $250,000 through $1,000,000 against $2,500, $3,500 and $5,000 a month, under three real-return bands: conservative (1%), moderate (3%) and higher (5%). Every balance gets a range, not a single number.
$250,000 starting balance
| Monthly withdrawal | Conservative (1% real return) | Moderate (3% real return) | Higher (5% real return) |
|---|---|---|---|
| $2,500/mo | 8 years, 8 months | 9 years, 7 months | 10 years, 9 months |
| $3,500/mo | 6 years, 2 months | 6 years, 7 months | 7 years, 1 month |
| $5,000/mo | 4 years, 3 months | 4 years, 5 months | 4 years, 8 months |
$500,000 starting balance
| Monthly withdrawal | Conservative (1% real return) | Moderate (3% real return) | Higher (5% real return) |
|---|---|---|---|
| $2,500/mo | 18 years, 3 months | 23 years | 34 years, 7 months |
| $3,500/mo | 12 years, 8 months | 14 years, 8 months | 17 years, 11 months |
| $5,000/mo | 8 years, 8 months | 9 years, 7 months | 10 years, 9 months |
$750,000 starting balance
| Monthly withdrawal | Conservative (1% real return) | Moderate (3% real return) | Higher (5% real return) |
|---|---|---|---|
| $2,500/mo | 28 years, 9 months | 45 years, 7 months | 50+ years |
| $3,500/mo | 19 years, 8 months | 25 years, 5 months | 42 years, 4 months |
| $5,000/mo | 13 years, 4 months | 15 years, 8 months | 19 years, 4 months |
$1,000,000 starting balance
| Monthly withdrawal | Conservative (1% real return) | Moderate (3% real return) | Higher (5% real return) |
|---|---|---|---|
| $2,500/mo | 40 years, 6 months | 50+ years | 50+ years |
| $3,500/mo | 27 years, 2 months | 41 years, 3 months | 50+ years |
| $5,000/mo | 18 years, 3 months | 23 years | 34 years, 7 months |
Every cell: monthly-compounded annuity depletion at the stated real return, a constant real withdrawal every month, capped at 50 years (shown as “50+ years” where the balance has not depleted by then). Formula published in full in the methodology below; independently re-derived and checked cell for cell before every deploy.
Common questions
People ask the same seven questions about runway and drawdown
How do I calculate my savings runway?
Divide your total accessible savings by your essential monthly spending. The result is the number of months your savings would cover essentials if your income stopped: $18,000 divided by $4,500 is 4.0 months, the calculator's own default example.
What counts as essential spending?
Housing, utilities, food, insurance, and minimum debt payments: the costs that do not stop when income does. Discretionary spending is usually cut first in a real shock, so a serious runway estimate leaves it out.
Is the 4% rule a runway answer?
No. The 4% rule is a first-year withdrawal RATE for a 30-year retirement, built from historical U.S. market data by William Bengen in 1994 and popularized by the 1998 Trinity study. It says nothing about a 5-year or 10-year runway question, and it assumes a specific stock-and-bond mix many accounts don't hold.
How long will $250,000 last in retirement?
$250,000 at $3,500 a month is a 16.8% annual withdrawal rate, well above the published safe-rate range on this page, so it empties inside a decade at all three real-return bands. Across the three bands here it runs 6 years, 2 months at the low end (1% real) to 7 years, 1 month at the high end (5% real), with 6 years, 7 months at a moderate 3% real return. The four-balance table above shows this starting balance and three others against three monthly withdrawal levels, at all three return bands.
How long will $500,000 last in retirement?
$500,000 at $3,500 a month is an 8.4% annual withdrawal rate, also above the published safe-rate range, and it clears a decade at every band but not two. Across the three bands here it runs 12 years, 8 months at the low end (1% real) to 17 years, 11 months at the high end (5% real), with 14 years, 8 months at a moderate 3% real return.
How long will $750,000 last in retirement?
$750,000 at $3,500 a month is a 5.6% annual withdrawal rate, still above the published safe-rate range, and the gap between its low and high bands runs over two decades. Across the three bands here it runs 19 years, 8 months at the low end (1% real) to 42 years, 4 months at the high end (5% real), with 25 years, 5 months at a moderate 3% real return.
How long will $1,000,000 last in retirement?
$1,000,000 at $3,500 a month is a 4.2% annual withdrawal rate, at the edge of the published safe-rate range, and at a 5% real return it does not empty inside this page's 50-year cap. Across the three bands here it runs 27 years, 2 months at the low end (1% real) to 50+ years at the high end (5% real), with 41 years, 3 months at a moderate 3% real return.
Kept current
Both tables above are a snapshot. Your own numbers should not be.
Every figure above is the same arithmetic run for round numbers you did not choose. Your own accessible savings, your own essential spending, your own balance and withdrawal move every time your accounts do, and a form you fill in once cannot keep up with that.
WealthAge brings your accounts, transactions, spending and cash flow into one place, connected or uploaded. The same arithmetic then runs on your connected accounts, not on the figures you typed in once.
See this run on your own accounts.
The rules of thumb
Three rules of thumb answer this question every day. You have probably used one of them this year.
Every common rule here is honest in one range and misleading past it
The 4% rule is a 30-year withdrawal rate, not a runway answer
William Bengen introduced the 4% rule in the Journal of Financial Planning in 1994, and the 1998 Trinity study (Cooley, Hubbard and Walz, AAII Journal) popularized it. Both built it from a specific setup: a 30-year retirement, historical U.S. market returns since 1926, 50 to 75% large-cap stocks with the rest in intermediate-term bonds, and a tax-free account. It is a first-year withdrawal rate, adjusted for inflation every year after, not a formula for how long a specific balance lasts.
It breaks in three places. It says nothing about a 5-year sabbatical or a 45-year early retirement, both outside its 30-year design. It ignores sequence risk: Morningstar’s State of Retirement Income (2025) found that retirees hit with weak returns in their first five years, who did not cut spending, were far more likely to run out of money than the 30-year average return would suggest. And the “safe” number itself moves: the same report’s base-case safe withdrawal rate drifted from 3.3% in 2021 to 3.9% in 2025, a rule sold as a constant that is, in practice, a research estimate that changes with market conditions.
Flat division is honest for a short horizon and misleading past about ten years
Flat division, savings divided by spending, is what the runway grid above computes, and it is the mental default most people already use. For a horizon measured in months it needs no correction, and none of the six corrects it. Past a decade it goes wrong in both directions. It assumes the money earns nothing, so it understates how long an invested balance lasts. It assumes prices never rise, so it cannot warn you when they do. The retirement scenarios table above exists because past that horizon, a real rate of return changes the answer by years, not months.
Three to six months of expenses is a savings target, not a duration model
“Save three to six months of expenses” is the one non-retirement rule of thumb people already use. It answers a different question, though. It tells you what to save toward, not how long the money you already have would last. The gap between that target and your own real number, computed above, is what this page was built to answer. The WealthAge Resilience Score, below, weighs that gap against everything else in your finances, not just this one number.
Your WealthAge score
A runway number by itself is a fact. What it means for you depends on everything else about your finances, and a rule of thumb cannot see any of that.
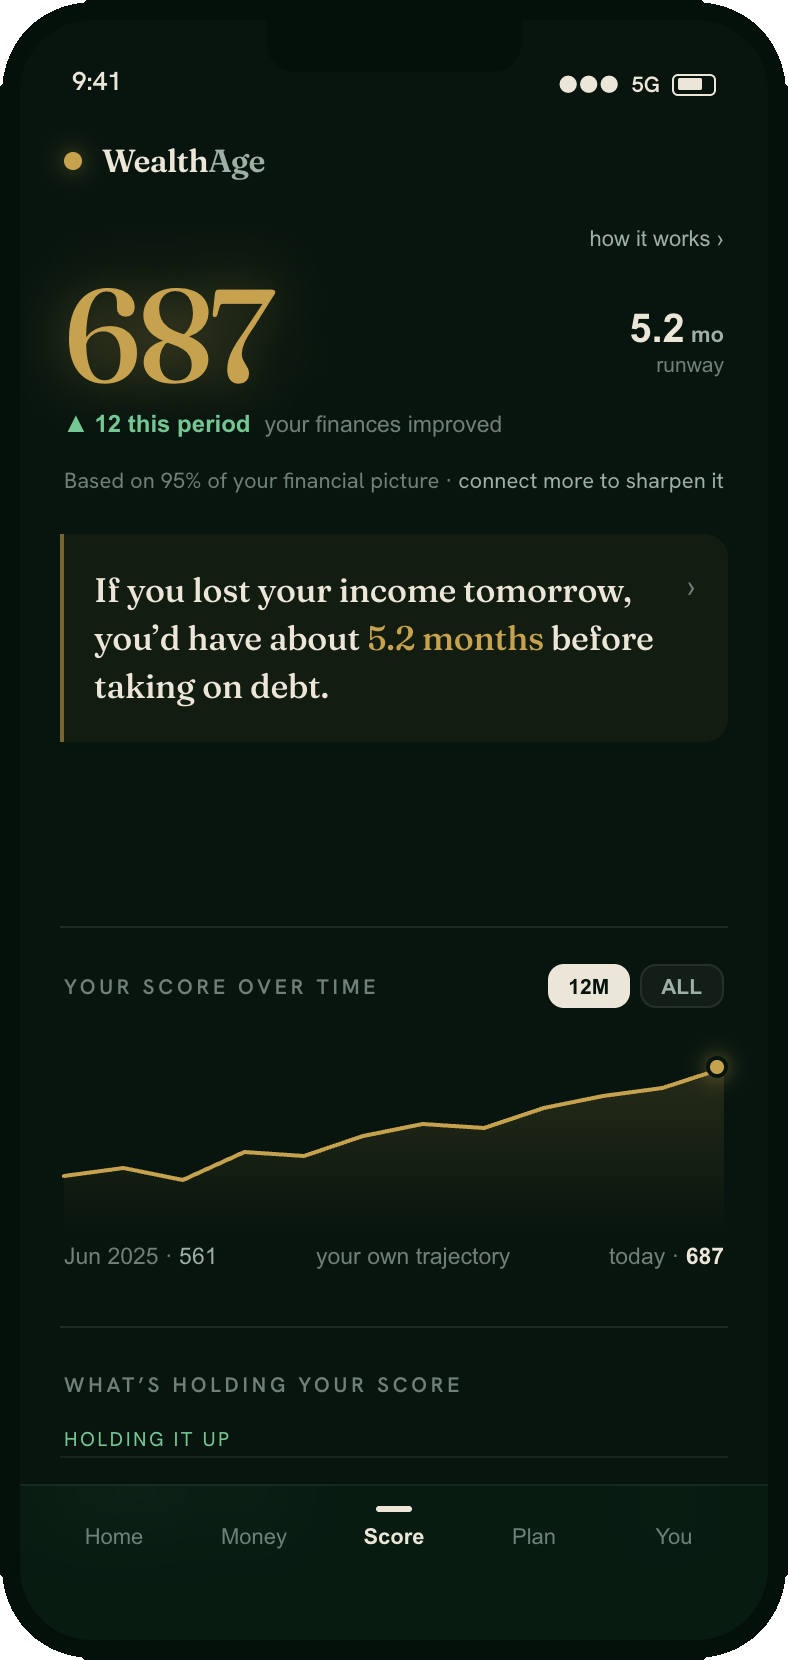
Runway is what your WealthAge score weighs heaviest
Liquid runway (the dimension this page computes a simplified version of) weighs heaviest of the six inputs behind a working household’s WealthAge score. The score’s own version starts from what you could actually reach in a crisis, then weighs committed costs, debt service, income adequacy, income replacement and protective context around it. A household already living on passive income is routed differently and is never scored on a missing paycheck; the method page shows both paths.
The free WealthAge resilience-score estimator asks six questions, no bank login, no card. If you want the by-age context behind your own net worth first, the net worth by age tool is the sibling page to this one. Full method: how the WealthAge Resilience Score works.
Connect or upload, and see your score against real runway.
Limits
Neither model on this page can see your actual life
Both figures above come from what you typed in.
What’s reachable. Both models take your accessible-savings and balance figures as given. Neither one checks whether a retirement account’s early-withdrawal penalty, a vesting schedule, or a CD’s maturity date would actually let you touch that money on the timeline the number implies.
Taxes. Neither model deducts taxes from a withdrawal or from investment growth. A taxable account and a tax-deferred one would deplete on different real timelines even from an identical starting balance.
Sequence risk. The retirement model applies one constant real return every month. A real market does not: two savers with the same 30-year average return can have very different outcomes depending on whether the bad years land early or late, and this model cannot show you which one you would get.
Everything else you have. Other income, insurance, a working spouse, family help: none of it is in either calculation. Treat both numbers as a starting estimate, not a guarantee.
Methodology
Every number on this page comes from one of two published formulas
The if-income-stopped mode and the runway grid table use flat division: accessible savings divided by essential monthly spending, rounded to one decimal month. No growth, no inflation, no market assumption of any kind.
Returns and withdrawals are both in today’s dollars. The bands are real returns, net of inflation: conservative 1%, moderate 3%, higher 5%. Your withdrawal stays constant in today’s dollars, which is what an inflation-matched withdrawal means. The retirement-drawdown mode and the scenarios table use monthly-compounded annuity depletion on that basis: a stated annual real return converts to a monthly rate ((1 + annual return)^(1/12) − 1), applied every month to the remaining balance before that month’s constant withdrawal is taken. CalcXML and the bank calculators in this category instead compound a nominal return and escalate the withdrawal every year to stand in for inflation; that convention does not apply here, where the return is already real and escalating the withdrawal on top of it would count inflation twice. The balance is simulated month by month until it can no longer cover a full month’s withdrawal; the month it runs out is resolved to a fraction (how much of that month’s withdrawal the remaining balance could actually cover), so the years-and-months figure is not rounded up to the next whole month. The simulation is capped at 50 years: past that, this page reports “50+ years” rather than a number from further out than any of the underlying return assumptions were ever meant to project.
Both formulas are the same arithmetic wherever it runs, so the tables and the calculator above cannot disagree. Every printed cell in both tables is checked against that exact formula before every publish, most recently on 10 August 2026.
Published 30 July 2026. Rebuilt on the band system 9 August 2026. Retirement-drawdown model corrected 10 August 2026.
Corrections: 2026-07-30: first publication. 2026-08-09: rebuilt on the band system, added the retirement-drawdown mode, the retirement scenarios table, and the sourced heuristic attack. 2026-08-10: the retirement-drawdown model paired a real return with an escalating withdrawal, which double-counted inflation; corrected to a constant real withdrawal, and every retirement-drawdown figure on this page recomputed.
Of the six pages in this family we checked on 9 August 2026 (Vanguard, Regions, CalcXML, SmartAsset, Bankrate and NerdWallet), only CalcXML asks for a tax bracket, and taxes are a real mechanic this page still does not model either. Five of the six ship a calculator, and on every one of them no number exists until it loads; the sixth, Vanguard, has no calculator at all. Every figure here is already printed on the page. And this is the only one of the six that answers the non-retirement question and the retirement question together, with a range instead of a single number.
A number is not a plan. Your own accounts are.
Both models above answer the question they were built for, and neither one can see your actual life: what you could reach quickly, what taxes take, what a bad first five years would do.
WealthAge runs the same arithmetic on your real accounts, connected or uploaded. It reads your runway against a simulated shock, not a rule of thumb.
WealthAge keeps this arithmetic running on your real accounts.
Connect or upload to start.
See how it works